This story is currently available in anglais only — a translation isn't ready yet.
Two ADNOC Vessels Struck in Hormuz, and the Dirham Doesn't Move
Tehran-Abu Dhabi tensions escalate at sea while the CBUAE peg holds at 3.6725 and SAMA sits at 3.7500 — the transmission mechanism, again, refuses to transmit.
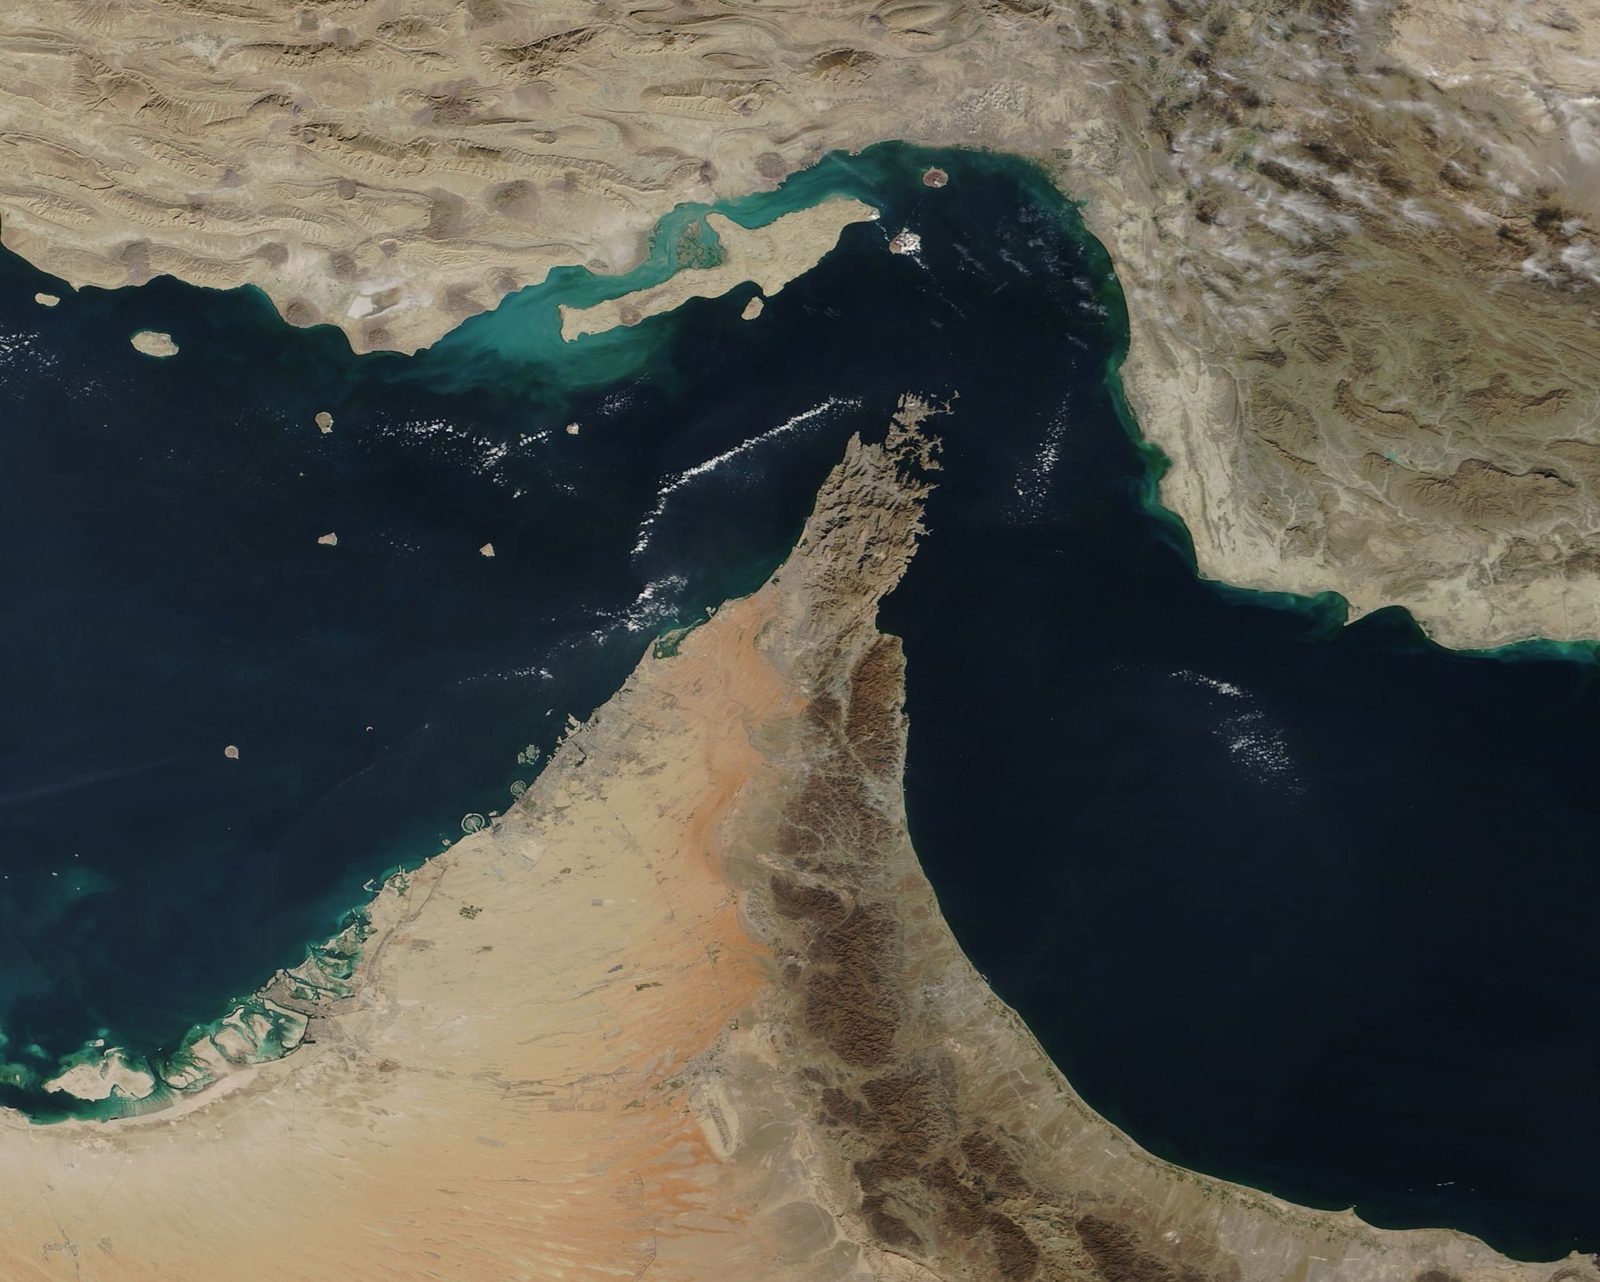
The overnight headline is not a price. It is that Iran struck two ADNOC vessels in the Strait of Hormuz, per the UAE's own account, with no injuries reported — and the dirham is trading where it traded on Sunday, at 3.6725 to the dollar. The riyal is at 3.7500. If you did not already know a maritime incident had occurred inside the world's most consequential oil chokepoint, the currency screens would not tell you.
This is worth pausing on, because it is the point most commentary misses. The AED and SAMA pegs are not opinions on geopolitics. They are policy instruments backed by reserves large enough to make speculation against them an expensive hobby. A Hormuz incident that would have moved a floating currency by a full figure moves these two by nothing, because the central banks have chosen — and can afford — for them not to move. The oil market carries the risk premium. The FX market carries the peg.
The mechanism to watch today is therefore not the currency but the freight and insurance chain behind it. War-risk premiums on Gulf hulls were already elevated before this week; a confirmed strike on ADNOC-flagged tonnage will widen them further, and that cost lands on realised export margins rather than on the exchange rate. Saudi Aramco's decision to route more crude through the East-West pipeline to the Mediterranean — a story that has been building for weeks — reads differently in light of last night. It is not a commercial optimisation. It is a hedge against exactly this.
US weekly crude production printed 13,805 thousand bpd for the week to 7 August, a number that continues to sit near the upper edge of its multi-year range and quietly caps how far any Hormuz premium can run before American supply absorbs it. That is the ceiling on today's oil tape, and it is why a genuine incident produces a real but bounded move rather than the vertical rip the headline alone would suggest.
Parallel to the maritime story, the UAE is reported to have released roughly $3bn in Iranian assets alongside gold and aircraft transfers. Read the two items together and the picture is less contradictory than it appears: Abu Dhabi is running de-escalation through the diplomatic channel while naming the attack through the security one. It is a familiar Gulf posture — talk and deter on separate frequencies — and the peg is the financial expression of the same doctrine. Stability is the product on offer.
For the session ahead, three things earn attention. Brent's opening premium and whether it holds past the European handover. Any CBUAE or SAMA liquidity operations, which would be the first quiet signal that reserves are being deployed rather than merely available. And the language from Riyadh — Turkey's proposed defence pact with Saudi Arabia and Pakistan is a slower-burning story, but a Hormuz incident is exactly the kind of context in which slow stories accelerate.
The pegs will end the day at 3.6725 and 3.7500. They almost always do. The interesting question is what everything around them had to absorb to keep it that way.