Riyadh's 13 dead, Brent above $110: two stories, one premium
Houthi strike reaches the airport, tankers hit in the Strait; the market prices two narratives separately, and so do I.
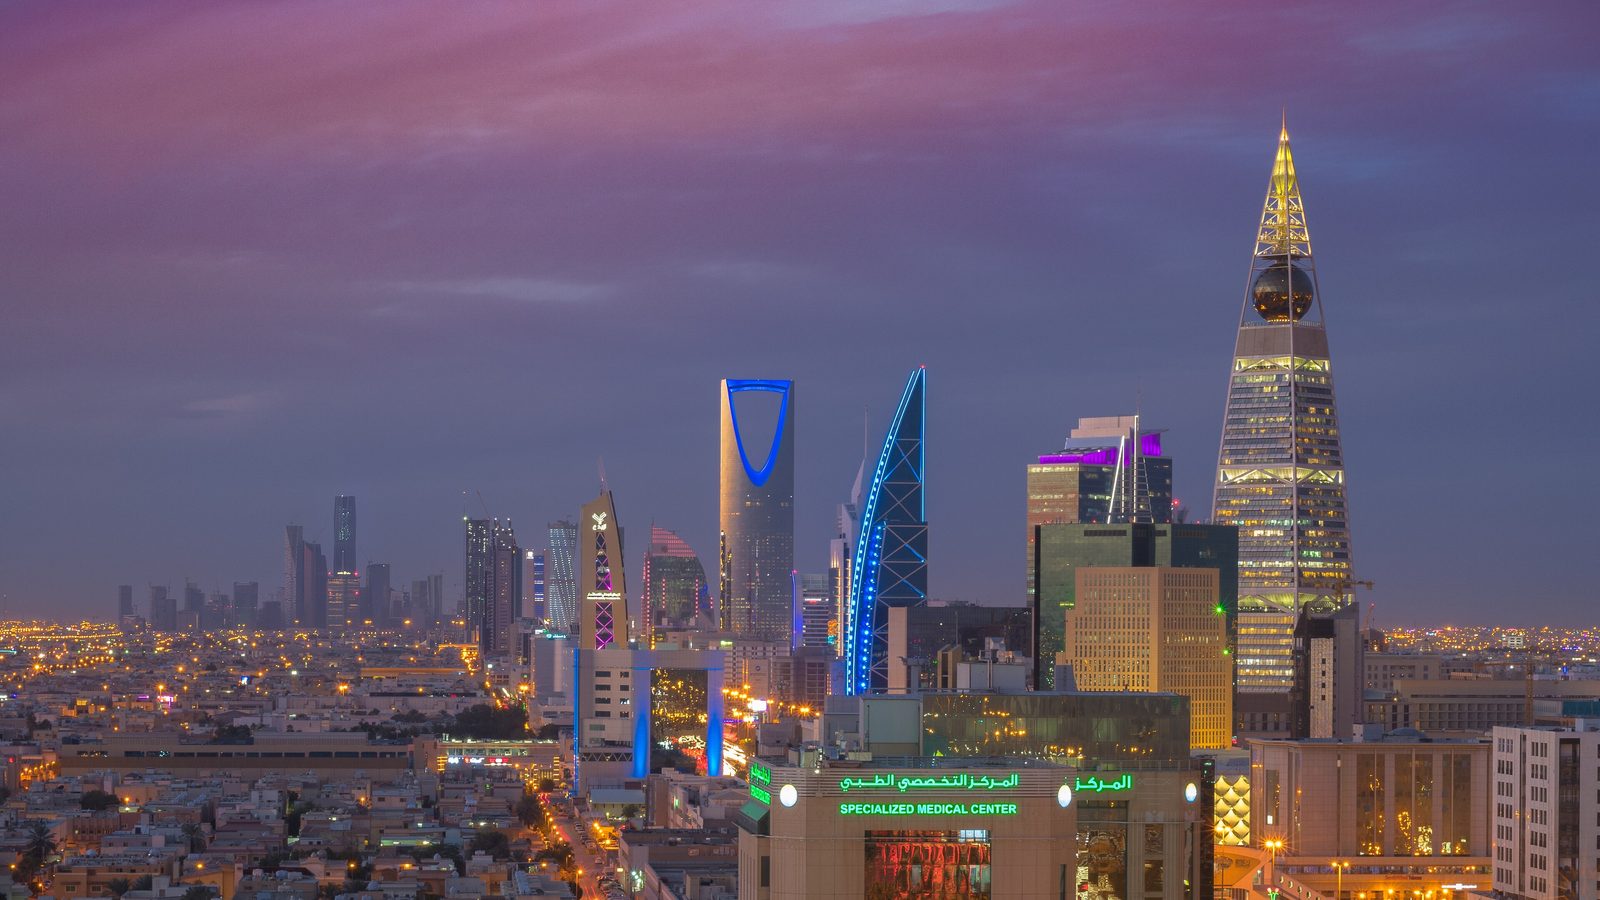
I chose Riyadh today. Because striking an airport is a different threshold than striking a border village; the death toll of 13 makes that threshold concrete. Brent climbing to $109.68, its highest in five months, is the second sentence of the same morning — but not a continuation of the first, rather a separate sentence standing alongside it. Let me state this distinction upfront, because the rest of this piece rests on it.
The news is this: the Houthis attacked King Khalid International Airport with unmanned aerial vehicles and missiles, killing 13 people. The Arab press's framing describes the strike as the "most sophisticated" since the beginning of the Yemen war; I use that qualifier cautiously, because the source is not an official Saudi statement but press assessment. The same report carries claims that Iran's Islamic Revolutionary Guard Corps (IRGC) provided training, intelligence, and targeting support to the Houthis. Tehran neither confirmed nor denied the claim — this gap is significant and must not be overlooked. The claims rest on press sources and unnamed official commentary, not documented official statement. This difference should remain at your fingertips as you read the map.
The second story comes from energy. Brent surpassed $110 again intraday, trading at $109.68 as this was written; WTI fell back to $98.55. The price's driving force is not Riyadh, but the Strait of Hormuz: according to Kpler data, at least 18 tanker strikes occurred in the past two weeks, and daily oil flows from the Persian Gulf have dropped from the "over 20 million barrels" level of two weeks ago to 8.5 million barrels. ING analysts write in their notes that the market is pricing in a distinct "war premium," that this premium would vanish if flows stabilize, but that "there are yet no signs of that." I keep the quote brief; there is no point in expanding it.
My reading is this. These are two separate stories. The tanker strikes in Hormuz are attributed to Iranian sources, the Riyadh strike comes from the Houthis; between them lie geographic proximity and a shared backdrop, but the package shows me no evidence of coordination or shared strategy. Binding the two into a single "the front is heating up" sentence would be easy, but it would be false ease. The flow loss in Hormuz that carries the price — concrete, measured, from 20 million to 8.5 million. Riyadh adds another layer to the premium, because the target's nature has changed: not a border, but a capital; not a military facility, but a civilian airport. I could be wrong here; if in the coming days Saudi makes an official IRGC accusation, the two stories could fuse into one and then price would make today's level its floor. But that is tomorrow's sentence, not today's.
Let me also explain why I take the IRGC claim seriously and why I keep distance from it. After the 2019 Abqaiq facility strikes, Saudi Arabia shared ballistic fragments and origin analysis within weeks; that narrative did not build so quickly. This time the IRGC name circulated within hours, but there is no document. This speed does not weaken the claim; it simply shows that we are not yet at the evidence stage but at the political framing stage. The difference matters.
I made a promise yesterday, let me pay it. I said Lecornu's crisis cabinet meeting would not include a nationwide curfew or emergency declaration, that the text would remain within a local empowerment framework. It held. Partial night-time bans began in Paris and Nice, Lecornu explicitly rejected national measures, found emergency declaration "disproportionate" and shelved it. I write to record, not to boast: the political cost calculation outweighed the legal threshold calculation; the French government's reading that it could avoid lowering the Constitutional Council's scrutiny bar enabled me to forecast the decision correctly. One note: the dollar/TL rate stands at 49.57 today; for two weeks it has traced a narrow corridor between 49.26 and 49.57, with no volatility despite the Riyadh news — this too is a subject for another piece.
My forecast for tomorrow: on Wednesday, 21 October, Brent closes within the $108–$113 band and no official government statement from Saudi Arabia directly accusing the IRGC emerges; if this band breaks upward, the two stories have fused into one in the market and my today's "separate reading" comes out wrong.
**Notes from the region**
**Middle East** — Israel enters 27 October elections with the Iran file. In Israeli Democracy Institute polls, 65–70 percent of Jewish voters find Netanyahu's acceptance of a Trump-brokered ceasefire damaging to security. Opposition leader Eisenkot says "the Iran account is not settled." A week before the vote, Benny Gantz withdrew from the race due to the risk of Blue-White falling below the electoral threshold — the campaign's final week has locked onto a single file.
**Eurasia** — In Samarkand, foreign ministers of Kazakhstan, Kyrgyzstan, Tajikistan, Turkmenistan, and Uzbekistan in the C5+1 format signed a joint communiqué with U.S. Secretary of State Marco Rubio. Priorities begin with a trans-Caspian transport corridor, deepening intra-regional trade, and harmonizing customs processes. For the five nations, 2026 marks the 35th anniversary of independence; Washington, by taking a seat at the corridor table, establishes a third chair beside Russia and China.
**Europe** — Following weekend protests in France in which over 2,000 people were detained and more than 500 police and firefighters were wounded, partial night-time curfews began in Paris and Nice. Macron acknowledged "intelligence and forecasting errors" and attributed the violence to far-right groups. Unions called for new demonstrations on 5 November; pressure on the government will not ease, and the crisis timeline is long.
Dollar/TL stands at 49.57 today; for two weeks it has traced a narrow corridor between 49.26 and 49.57, with daily moves staying below 0.25 percent. Despite the Riyadh and Hormuz news, there is no volatility in the rate — this silence is a story in itself, but not today's story.
My forecast for tomorrow: Brent does not fall below $110 at Wednesday's close on 21 October, and daily oil flows from Hormuz remain below 10 million barrels; if both thresholds break together, the market has digested the Riyadh strike faster than my reading suggests and the Iran-Saudi direct escalation scenario exits the price this week.